Renewals and smarter mortgages
Your bank sends a blanket renewal rate, not a check-in phone call to see how your mortgage has been working for you.
A renewal letter is your bank's opening offer, written on the assumption you'll sign it. Send it to me and I'll show you, on a short video, how it compares with what else is available.
A mortgage renewal is the point where your current term ends and you agree a new rate and term for what you still owe. You can stay with your lender or move to another one, and renewal is the easiest time to compare.
Send me the letter. I'll send you a video.
Take a photo of your renewal letter, or forward the email.
I look at the rate, the term and the fine print, and compare it with what other lenders would offer you.
You get a short video back, usually within 24 hours, showing the difference in dollars.
No cost. No obligation. If your bank's offer is the right one, I'll tell you to sign it.
Your letter is used only to prepare your comparison.
What happens, and when.
1
About six months out
What happens: You book a check-in call.
What to do: Start the conversation to see where you're at and how your current mortgage is doing for you. Nothing is committed, just a catch up.
2
About four months out
What happens: I line the offers up in writing so you can see the difference in dollars.
What to do: Compare offers while there is time to move.
3
The last three weeks
What happens: I finalize anything still missing.
What to do: Decide. Signing by default is still a decision.
AN OFFSET MORTGAGE, WORTH KNOWING ABOUT
How an offset mortgage works
An offset mortgage links your mortgage to your everyday accounts. Your money keeps working for you while it sits there, and it's still yours to use.
It sounds unusual because most people have never been offered one. It isn't a trick, and it isn't for everyone.
I'll show you with your own numbers whether it helps.
See the example in numbers
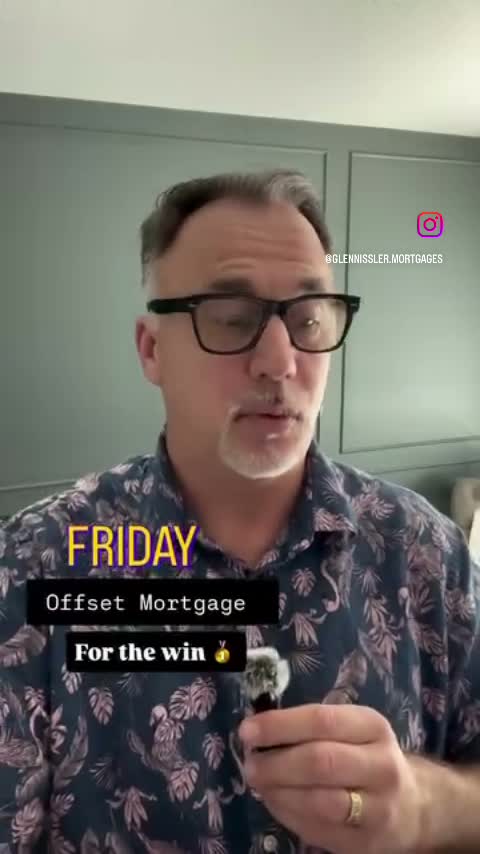
- Glenn compares a client’s upcoming renewal with what the bank is likely to offer, using a $600,000 mortgage at around 4% as the example.
- An offset mortgage brings the mortgage, savings and paycheque together in one place.
- In this example that means being debt-free in about 11.5 years instead of 30, and paying far less than the $435,000 in interest the bank’s standard option would cost.
- His point is that the strategy looks at the client’s whole financial picture, not just the rate.
Illustration only. Not a rate quote.
When will you actually be done?
Every time you renew, your bank can quietly stretch the finish line. I'll show you your mortgage-free date as it stands today, and what would bring it closer: payment frequency, lump sums, or a different structure.
Could you do this yourself? Yes. Here's how.
These are the questions I'd ask any lender. Take them to your bank. If you'd rather have someone ask them for you, that's what I do.
Common questions
Should I just sign my renewal letter?
Not before you've compared it. A renewal letter is your lender's opening offer, and it's often not their best one. Signing is easy, which is exactly why so many people do it. A short review tells you whether the offer is fair, and if it is, you sign knowing that for certain.
When should I start looking at my renewal?
Four to six months before your term ends. That's enough time to compare lenders, hold a rate while you decide, and switch without rushing if switching makes sense. Your lender's renewal letter may not arrive until a few weeks before your maturity date, which leaves very little room to look around.
Can I switch lenders at renewal, and does it cost anything?
Yes. At your renewal date you can move to a new lender without a prepayment penalty. If you're moving the same balance and not extending your amortization, you generally don't have to re-pass the mortgage stress test either. There are legal and discharge costs involved in a switch, and the new lender often covers most or all of them. I'll lay out any cost in writing first so you can see whether the savings are worth it.
Does comparing lenders affect my credit score?
Very little. I check your credit once and use that single report to compare options across lenders, rather than each lender checking separately. One inquiry may lower your score by a few points for a short time, and it recovers.
What is an offset mortgage?
It's a mortgage and your everyday banking combined in one account. Your income is deposited straight against what you owe, so your balance drops the day you're paid and you're charged interest on a smaller amount. You still spend from the account as you normally would. The money that would otherwise sit in chequing is quietly working against your mortgage in the meantime.
Who offers offset mortgages in Canada?
Manulife Bank's Manulife One is the best known, and it's the one I work with most. A few other lenders offer accounts that combine a mortgage with a line of credit, but they don't all work the same way. I'll show you how each would behave with your actual income and spending.
Is an offset mortgage the same as a line of credit?
They're related, but not the same. A home equity line of credit usually sits beside your mortgage as a separate account you borrow from when you need it. An offset mortgage brings your mortgage, income, and savings into one account, so every dollar you hold reduces your interest daily. It does take discipline. Because the funds are easy to access, it works best for people who keep a close eye on their spending.
How can I pay my mortgage off faster?
A few small habits make the biggest difference. Switch to accelerated bi-weekly payments. Use your annual prepayment privilege when extra money comes in. If your rate drops at renewal, keep your payment where it was instead of letting it fall. And choose a mortgage structure that suits how you earn, which for some people is an offset mortgage. We can map out what each of these would save you.
What does it cost to have you review my renewal?
No cost. No obligation. If your bank's offer is the right one, I'll tell you to sign it.
What if my bank's offer turns out to be the best one?
Then I'll tell you so, and you sign it. It happens. You'll have lost nothing, there's no fee, and you'll know your offer held up against the alternatives.